The Objection Handling Funnel: Cole Gordon's 60 Minutes
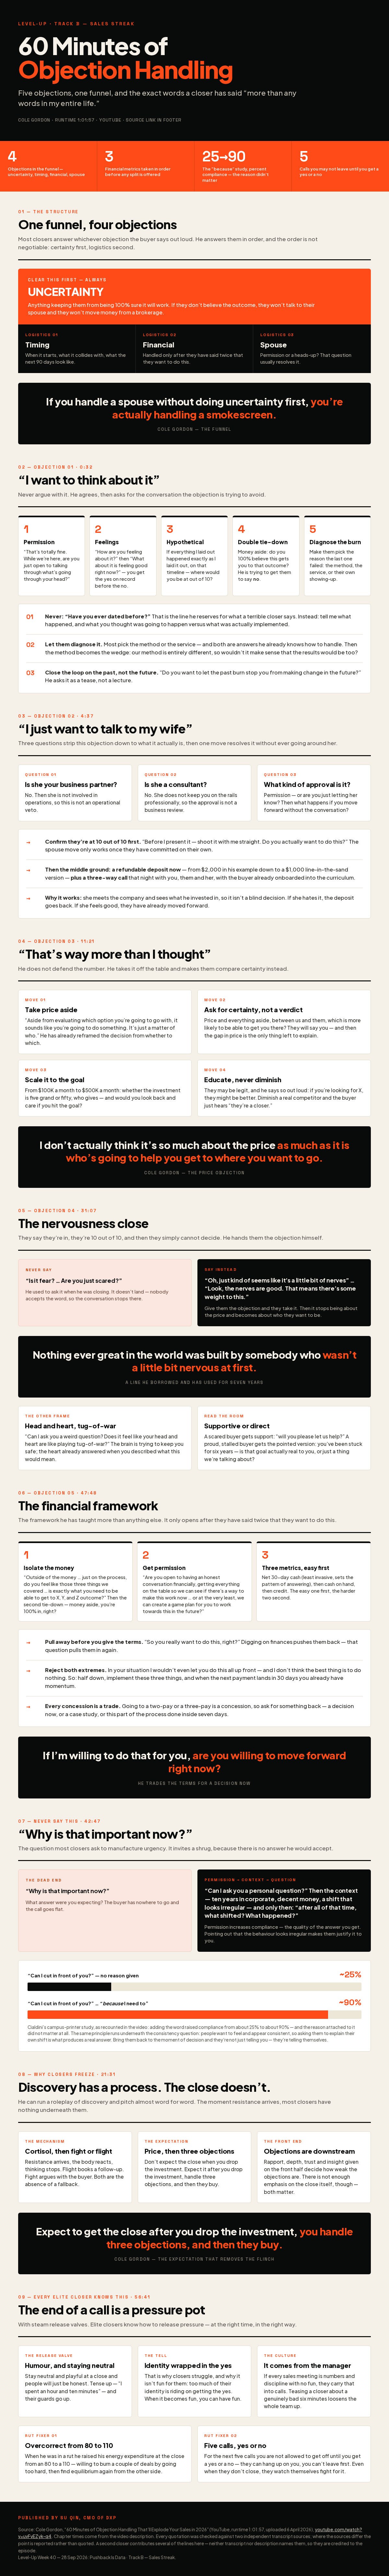
An hour of Cole Gordon on the five objections that actually show up, why one of them has to be cleared before the other three mean anything, and the sentence he has repeated more than any other in his life.
He says he has spoken these words more than any other words in his entire life. Not a mission statement, not a pitch opener. A single sentence he deploys at the exact moment a deal starts to wobble, and it has been working since 2017.
The video runs an hour and one minute. Most of it is two experienced closers roleplaying objections back and forth, which is why it is worth the time — you hear the pushback and the response in the same breath, with no edit between them. What follows is the structure underneath all of that talking, because the structure is the part you can actually steal.
Objection handling is a funnel, and the order is not negotiable
Most closers answer whichever objection the buyer says out loud. He answers them in order, and the order does the work.
There are four. Uncertainty sits at the top and it is the only one that is not logistical. Below it are timing, financial, and spouse, three logistics that all behave the same way. Uncertainty comes first because a buyer who does not believe the outcome will not go talk to their spouse about it, and will not move money out of a brokerage to pay for it. He is blunt about what happens when you invert the sequence. Handle a spouse objection without clearing uncertainty first and you are actually handling a smokescreen. You solved the conversation the buyer was willing to have, while the real objection sat untouched underneath it.
This is the single most useful idea in the hour. Every objection you hear is either uncertainty wearing a costume, or a genuine logistics problem sitting behind a belief problem. Learn to tell them apart in the first thirty seconds and the rest of the call gets much shorter.
"I want to think about it"
He never argues with it. He agrees — "that's totally fine" — and then asks for the conversation the objection was designed to avoid. Are you open to talking through what's going through your head?
From there it is a five-step ladder. How are you feeling about it, and what about it is feeling good right now (you get their enthusiasm on record before their hesitation). Then the hypothetical: if everything I laid out happened exactly as I laid it out, on that timeline, where would you be out of ten? Then the double tie-down: money aside, do you 100% believe this gets you to that outcome? He is explicitly trying to get them to say no. If they say yes anyway, the rest is logistics. If they say no, you have found the actual objection instead of the polite one.
The last step is the one people skip. He makes them diagnose why the previous vendor failed, and he offers exactly three options: the method was wrong, the service was bad, or they didn't show up themselves. Most buyers pick the first two, and both are answers he already knows how to handle, because the method is the thing he is about to differentiate on.
He is equally clear about what not to say. The temptation is a clever reframing ("have you ever dated before?"), and he files that under what a terrible closer says. It is a gotcha, and gotchas put people's guards up.
The spouse objection
Three questions strip this down. Is she your business partner? Is she a consultant? So what kind of approval is this? If she is neither of the first two, the approval is not an operational review, and it is worth saying that out loud without being rude about it.
Then the move. Confirm they are at a ten out of ten first. Before any solution is offered, he asks them to shoot straight about whether they actually want to do this. Only then does he propose the middle ground: a refundable deposit now (two thousand dollars in the example, a thousand in a softer version of the same play), plus a three-way call that night where the buyer has already been onboarded into the curriculum.
Why that works is worth writing down. She meets the company instead of hearing about them. She sees what was actually bought instead of guessing. And if she hates it, the deposit goes back, so the buyer takes the step without ever going around her.
"That's way more than I thought"
He does not defend the number. He takes it off the table and makes them compare certainty instead.
First move: point out that the decision has already changed shape. They are going to do something, and the only open question is who. Second move: price and everything aside, between us and the other option, which is more likely to get you there? They will say you, and now the price gap is the last thing left standing.
Third move scales it. Going from a hundred grand a month to five hundred: whether the investment is five grand or fifty, who cares? And would you look back and care at all if you hit the goal? Then, quietly, the discipline that keeps this from becoming sleazy. If the other option is genuinely better for what they want, he says so on the call. Diminish a real competitor and the buyer hears one thing: they're a closer.
The nervousness close
They've said yes. They're a ten out of ten. And then they simply cannot decide.
He handles this by handing them the objection himself. Never ask "is it fear?" — he used to, and nobody accepts that word, so the conversation stops there. Instead: it's just a little bit of nerves. The nerves are good, that means there's some weight to this. Then the line he borrowed seven years ago and has never replaced: nothing ever great in the world was built by somebody who wasn't a little bit nervous at first.
There is a companion frame for buyers whose head and heart are visibly at war. Ask whether it feels like they're playing tug-of-war, and then name what is happening: the brain is trying to keep them safe, the heart already answered when they described what this would mean.
Underneath both sits a read-the-room judgment. A scared buyer needs support: will you please let us help. A proud, stalled buyer needs the pointed version — you've been stuck for six years, so is that goal actually real to you, or is it just a thing we're talking about? Same objection, opposite delivery.
The financial framework
This is the framework he has taught more than anything else, and it has a precondition: they have to have already told you twice that they want to do this.
Isolate the money first. Outside of the money, just on the process: do you feel those three things we covered are exactly what you need to get to that outcome? Money aside, you're 100% in, right? Then permission: are you open to having an honest conversation financially, getting everything on the table so we can see if there's a way to make this work now, or at the very least, create a game plan for you to work towards this in the future?
Then three metrics, asked in a deliberate order. Net 30-day cash first, because it is the least invasive and it puts them in the pattern of answering. Cash on hand second. Credit third. Easy one first, harder two after.
Now pull away: so you really want to do this, right? That reverses the pressure created by the digging. Then he rejects both extremes: in your situation I wouldn't even let you do this all up front, and I don't think the answer is to do nothing. So he offers the split, with momentum built into it so the next payment feels like an afterthought.
The sentence that closes it: if I'm willing to do that for you, are you willing to move forward right now? Every concession gets traded for something. Usually a decision now. Sometimes a case study, or this part of the process finished inside seven days.
Never ask why it's important now
"Why is that important now?" is the question closers reach for to manufacture urgency. He calls it a question where you have to wonder what answer you were expecting. The buyer shrinks, and the call goes flat.
The replacement is permission, then context, then question. Can I ask you a personal question? You've been in corporate ten years, you're making decent money — after all of that time, what shifted? What happened?
The mechanics he cites are real. Permission increases compliance, meaning the quality of the answer you get back. Pointing out that a behaviour looks irregular forces them to justify it, and consistency is the principle doing the lifting: people want to feel and appear consistent to themselves. He also recounts the campus-printer study where adding the word "because" took compliance from about 25% to about 90%, and the reason attached to it did not matter at all.
The payoff is that when they describe the moment it shifted, they are not just telling you. They're telling themselves.
Why closers freeze
Discovery and pitch have a process. Closers never forget what to say in either one, because they trained on it. The close is where the training usually stops, and it shows: resistance arrives, cortisol follows, thinking stops. Flight books a follow-up. Fight argues with the buyer. Both are the absence of a fallback.
So he sets the expectation that removes the flinch. Don't expect the close when you drop the investment. Expect it after you drop the investment, handle three objections, and then they buy. When that is what you expect, you can usually guess what they're about to say, and you're not angry when it isn't a yes.
He is careful with this, though. Weak objections are usually downstream of weak discovery: rapport, depth, trust, and the insight you gave early. Both halves matter, and the industry's current line — an objection means you're not a good closer — is propaganda.
The pressure pot
The end of a call is a pressure pot with steam release valves, and elite closers know how to release pressure at the right time and in the right way. Usually with humour. Stay neutral and playful at a close and people just tell you the truth; tense up because you've spent an hour and ten minutes on this one, and their guards go up.
The tell is identity. Closers who struggle have too much of it wrapped up in getting the yes. When it becomes fun, you can have fun. And when you're having fun, you can ask the hard question without it landing like an accusation.
Two fixes for a rut, both physical. First, overcorrect: he used to raise his energy at the close from an 80 to a 110, willing to burn a couple of deals by going too hard, just to find equilibrium from the other side. Second, for the next five calls you are not allowed to get off until you get a yes or a no. They can hang up on you. You can't leave first.
Neither works if the culture is wrong, and he puts that on the manager. If every sales meeting is numbers and discipline with no fun in it, the team carries that into the call.
Source: Cole Gordon, "60 Minutes of Objection Handling That'll Explode Your Sales in 2026" (YouTube, runtime 1:01:57, uploaded 6 April 2026). Every quotation was checked against two independent transcript sources. Published by Su Qin, CMO of DXP.
Working on something similar? Fastest over WhatsApp.
Message me on WhatsApp →